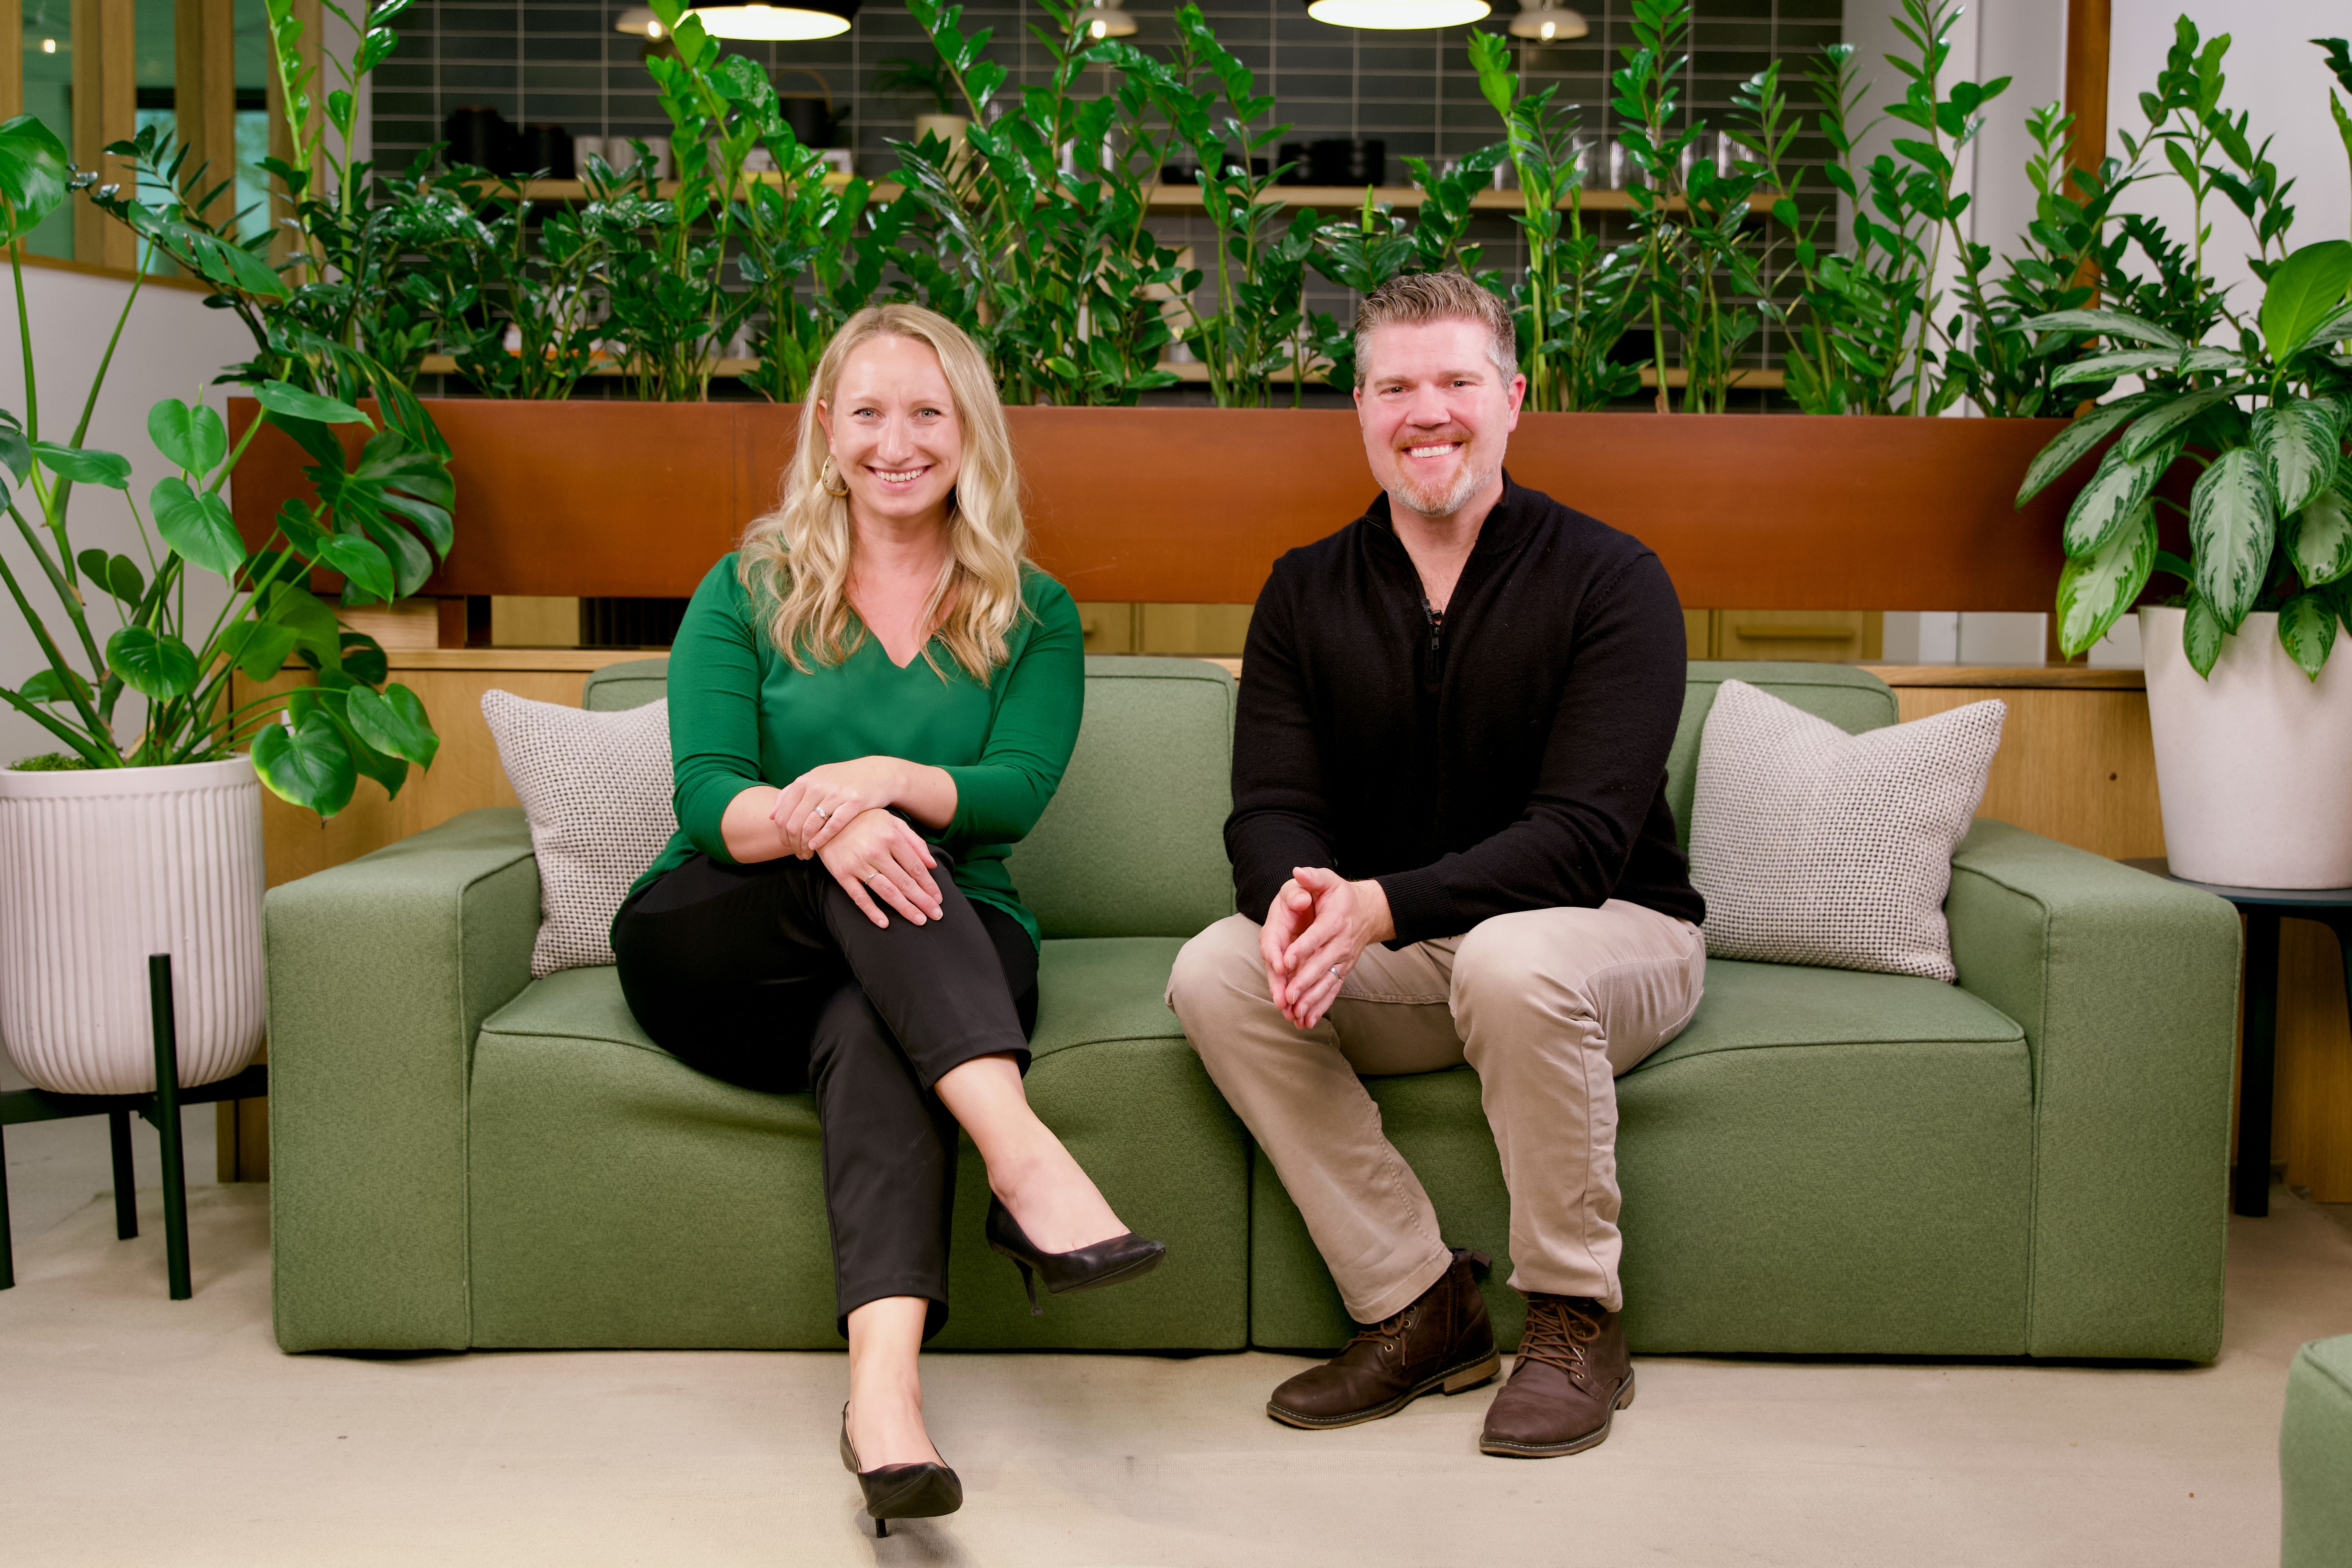
Beau Wirick: HAHAHAH fake laugh, fake laugh
Stacey McKinnon: Ridiculous.
Beau Wirick: We're ridiculous. Yeah, we're obviously cool.
Stacey McKinnon: Yeah
Beau Wirick: We're obviously fun. We're obviously young. We're modern.
Stacey McKinnon: Modern.
Beau Wirick: Modern.
Stacey McKinnon: I mean that's perfect.
Beau Wirick: That's perfect. What an intro to our conversation about Modearn.
Stacey McKinnon: Yes.
Beau Wirick: Stacey, you are the Modearn mama. You created Modearn out of nothing. So tell us, why do we have this offering? Like, where did this come from in your mind?
Stacey McKinnon: This is something that means a lot to me. I actually was reflecting on it more recently as we were talking about doing this episode and just thinking about the journey we've been on with Modearn because it started 2 or 3 years ago. But for me personally, I actually take it back to even like my childhood. I grew up in a very small town in Northern California, Lake Tahoe, where financial advice, financial decision making, financial literacy was just not a part of the equation. I mean, my biggest concern growing up was like, when is the plow going to come so we could go to school in the winter?
Beau Wirick: It was not because you have that white stuff that falls from the sky?
Stacey McKinnon: Yeah. Or, you know, we did field trips where we learned how to build igloos just in case we were ever caught outside by ourselves.
Beau Wirick: Like, same here in Huntington Beach.
Stacey McKinnon: Yeah. Yeah. Not the same. Not the same. But, I mean, I'm sure that your story is probably similar. Like, almost none of us were taught finance growing up. And so we're like in this world today where we have to make financial decisions every day and we're not taught how to do it well. And I've been with Morton for 11 years, and I often times think if I wouldn't have been like landed in this industry, then I don't know that I would know how to make good decisions for my family. I would have been left with Google advice, which is not good advice because it doesn't know me as a person, as a human. And so just in like reflecting on that, we thought to ourselves, I bet other people feel this way. I bet other people are in a situation where they have tons of choices they need to make.
They have a lot of stress they're left with like DIY Google advice. There's no one to call. And so we wanted to fix that. And that's really where modern evolved from this place where we want more people to have access to good advice when they need it. And that's what we think is really meaningful about this.
Beau Wirick: Okay. So yeah, so that's the origin of where Modearn came from. What are the problems that we're trying to solve with the modern offering?
Stacey McKinnon: Yeah, I think that there's a few things that most Modearn clients face. But the first I would say is that generally speaking, they've built a good foundation. These Modearn clients are, generally speaking, millennial Gen X, maybe Gen Z. They've started their careers, they've launched their careers, maybe they started businesses. Some of them have bought homes, have started families. And so they feel like there's a foundation, but they're just not sure how to get ahead. I mean, you and I know it's so expensive to be a person in your 30s. In today's world, things just cost more than they used to. And so you have this collection and group of people who are always trying to figure out how do they get ahead while still paying for what they need to pay for in their life today. And so that's one major problem I think a lot of Modearn clients face.
Beau Wirick: And a lot of the times we have like parents who are like, oh, you know, when I was your age, I just did it like this and this, and it's almost like it doesn't apply to our situation a lot of the time. So where do I go? Yeah.
Stacey McKinnon: I mean, our parents generation had more money than we have. And so you think to yourself, how do I get to a place where they got to. And that's really tough. I would say the second thing that a lot of clients are struggling with is this dynamic we call current me versus future me. Current me wants to go on vacation like once a month, but future me is like, retirement could also be a vacation that you have to plan for, and that's going to happen. It's almost inevitable. So can you take a vacation all the time, or should you actually be saving that money for retirement?
Beau Wirick: So I listen to current me a lot. Yes. Is that a problem?
Stacey McKinnon: Well, you know, it's like that. Like old devil angel on your shoulders being like, what do you do?
Beau Wirick: Right, right.
Stacey McKinnon: The answer to that equation is probably somewhere in the middle. But we, most of our Modearn clients are working through that. And then the last thing I would say is that for most people, financial advice isn't accessible unless you have a certain amount of money. It historically speaking, advisors wouldn't even talk to you. So you are left with that. Like Google advice I was sharing earlier, or a DIY do it yourself type model.
And so I think a lot of our modern clients, something they're very grateful for, in fact, is that they don't have to do it alone. But it's a big problem. Most people don't have access to good financial advice.
Beau Wirick: And that's right. I mean, we take we're in this industry, right? And so if I have a client who, let's say, has $10 million and they're paying me a 1%, you know, AUM fee, it's natural for me to spend more of my energy to serve that client than if someone has $100,000. Right. It just there's a there's a huge disconnect in what people need and what we're incentivized to give. And so modern is basically bridging that gap. It's basically like hey, we are here. We want to serve this cohort of people who needs advice a lot. And so yeah, with that being said, tell us nuts and bolts like what is the modern offering.
Stacey McKinnon: Well, just to comment on what you just said, first of all, I'd like fight against that antiquated model just because people have more money doesn't mean that they that other people who don't have as much money don't need equally good advice. Right? And so if we can provide good advice, no matter how much you've already built, I think that's our number one objective.
When it comes to the actual service offering. We've gone through a few iterations of this, but I think it's pretty cool where it's landed. So one of the things that we've reflected on as a team is that most clients need help making decisions. It's all about the modern decisions that we have in our lives that are complex and they're multifaceted, and we just need support in making those decisions for the offering.
In general, we like to think about it as four different buckets of decision making that most people are faced with on a daily basis. The first one could be life. This might look like what state should I live in to pay the least amount of state taxes? This could also look like a spending strategy where we take the inflows and outflows and we say, what's the smartest way to spend?
The second category is family. This could look like talking to clients about who's the guardian of their children. If something were to happen to them, how much insurance is enough insurance to have? Or it could look like the dynamic of how do I pay for both private school and college? Do I have to choose one or the other, or is there a strategy I can, put into place that allows me to do both?
The third category...
Beau Wirick: Rob a bank and then you're fine. You can do both.
Stacey McKinnon: Maybe not that one.
Beau Wirick: This is not financial advice.
Stacey McKinnon: The third one I would say is career. So sometimes our modern clients are business owners and they need help. Maybe strategically tax planning. What can I do is write offs versus not. Some of them work for your companies and they have stock options and they have to navigate through how to handle those. Maybe they have benefits packages and they're not sure how to maximize the benefits.
And then the fourth category is investments. So oftentimes our modern clients are investing in their 401K's or their retirement accounts. But they're starting to build personal wealth. And they have questions like, should I buy an investment property? Should I rent it out and get passive income? Should I invest in a portfolio? And so within all of these four categories, there's a lot of complexities between life, family, career and investments. A lot of big decisions to be made.
Beau Wirick: Yeah, it's kind of like if you and I just look at our text messages that we get from our friends.
Stacey McKinnon: Yeah.
Beau Wirick: All right. It's just that it basically has built out what the Modearn offering is.
Exactly. It's right.
Stacey McKinnon: It's exactly what it is. You're just like, wow, overwhelming information. And how do I digest it and make smart decisions. And so the second thing we've done is not only, cater the offering around those four categories, but we created three different tiers. And that's really a reflection of making sure we meet people where they are in life.
Tier one is really for people who are just building a foundation. I like to think of this as like the financial health checkup tier, where we're part concierge doctor, part personal trainer, going through all those four categories of decision making and kind of creating a really cohesive plan for our clients.
The second tier builds on the first, but then we layer in investment management. So oftentimes our modern clients maybe have built a few hundred thousand dollars in investments. They're looking for like a really smart savings strategy. They want to know how much should I put in for my 401k? How much should I put into an investment account? How do I actually build and grow my wealth?
And then the third tier is really everything put together, including access to a lot of our unique investment opportunities. You know, we've been a firm that's been around for over 40 years. We've specialized in doing alternative investments. And so that last tier really helps people to get access to unique opportunities that they wouldn't necessarily be able to access in, like something like their 401 K. And so that's kind of the scope of what the offering looks like.
Beau Wirick: Yeah. So the first tier is basically advice. The second tier is a blend between advice and investments. And the third tier is advice, investments, estate planning. Like everything that we offer as a company, you're getting the full suite.
Stacey McKinnon: Yep yep yeah
Beau Wirick: okay. And usually when people come to us, oftentimes if they're in their 30s or 40s, they're not quite at that third tier. But they still need us and we're still passionate about helping them.
Stacey McKinnon: A lot of people want to get to that third tier, though. So I think the basics of doing the first tier, the second tier, the third tier, that's how we see people journey through often as well.
Beau Wirick: Yeah. And we don't want to all of a sudden engage someone when they're 65 years old and ready to retire. Like all of the all of the advice and the relationship that we have with someone for 30 years leading up to that point, like that's where the good stuff really is a lot of the times. So we want to be able to establish that relationship.
Stacey McKinnon: You're building on something, right? And so that's something that's really special and it's nice. I think the entire modern offering is a very relational approach. It's about having a partner. It's about having somebody that's there for you need when you need them.
Beau Wirick: Yeah. So tell me about responses that you've gotten from clients of the value that we've been able to add to their lives with the modern offering.
Stacey McKinnon: So many good responses. I think my favorite one was I got an email from somebody that just said, I'm so glad that I have someone to call. I reflect on that and just the value of having somebody to call when you have all these decisions you need to make when life gets complex, maybe when you even have a disagreement between your spouse as to what the right direction is to go in. Having someone to call, I think is such a important aspect of this. Probably the second piece of feedback I've heard is that they love having an accountability partner, and this piece of feedback is not for everyone, by the way, because some people like accountability partners and some people are like X on the accountability.
Beau Wirick: I do want a personal trainer. Yeah, I want to go to the gym and just lay there.
Stacey McKinnon: But what I've heard from people is they actually like it. That we're going to check in with them. They like it that they have to stay on the spending strategy because they know that they're going to have a call with us in a month, and they want to say, hey, I did what we planned on. I executed, I made the right decision or the good decision for my family that we had agreed upon. And so having that accountability partner up oftentimes, I think, helps people to actually scale up on the right track, as opposed to continuing to maybe let spending take control of them. And finally, the last thing I would I would share is that a lot of our clients like getting access to more investments in their own case. Like I mentioned, they only have really stocks and bonds. And so when we're able to layer on more real investments that you can touch and feel and see like real estate or maybe loans backed by real assets, they're really excited about the opportunity to continue evolving their investment strategy and get access to more and more things.
Beau Wirick: Those are texts that I get all the time, like, hey, I'm scared of the stock market.
Stacey McKinnon: Right?
Beau Wirick: Where do I invest? Right? And so that's where that tier two or the investment strategy really comes in.
Stacey McKinnon: It's really it's really nice to be able to offer that to clients. Yeah. Well I just described the overview of the offering, but I think it might be helpful if we give people real examples of how we help Modearn clients. So would you mind just sharing a few examples?
Beau Wirick: Yeah. I think when people are like, am I a Modearn client? It's easier to describe how we've helped people, and then you can say, oh, that's me.
Stacey McKinnon: Yeah.
Beau Wirick: So I think there's three in my experience. And we've been doing been doing this for a couple of years now. In my experience, there's three ways that we've really been able to help clients like modern clients.
One is in real estate. I mean, buying and selling real estate, rent or buy those decisions are huge decisions for people in our stage of life. Secondly, investments kind of like what you were just talking about. How do I invest my money? How do I diversify correctly? And then thirdly, is education planning, because a lot of modern clients have young kids. And you read a lot about, you know, 529 plans and educate how expensive colleges. And so that's like right on your like the the top of your mind the moment you have a kid.
Stacey McKinnon: Totally.
Beau Wirick: And so I think those are the three categories that I've seen the most, the most that we've been able to help people. And so, so just like as an example, real estate, you've had these conversations. I mean, what's an example of helping someone with real estate that you've run into?
Stacey McKinnon: Well, I think one of the most challenging things that Modearn clients experience is just the conundrum of how do I invest in real estate? Because that's the way that my family built their wealth, right? Often times we look at real estate historically and we say, wow, that was one of the best places to invest.
Stacey McKinnon: Real estate is the best place to invest. But, I don't know if the past predicts the future. Right. And you have to ask yourself these questions. And I was working with a CPA actually recently who we were talking about a client scenario and they have some pieces of real estate. And I said, hey, you know, I think it's probably best that they sell that real estate. And the CPA was like, whoa, whoa, whoa, whoa, whoa. I work with so many clients. They've built their wealth in real estate. How could you ever recommend to the client to sell the real estate? And I said, let's just get into the numbers. And, you know, CPAs love the numbers. So we got into the numbers. Yeah. And we looked at these real estate properties and they were making between 1 and 3% returns.
Beau Wirick: Crazy.
Stacey McKinnon: You can make more in U.S. treasuries.
Beau Wirick: Right.
Stacey McKinnon: And where the properties are located, the growth projections of real estate, meaning the value of that real estate. It's projected to flatline or maybe even decline in some of these areas. And so when you look at a flatlining real estate market and 1 to 3% returns, all of a sudden your eyes are open to, oh, maybe real estate isn't the same investment it was in the past.
There's definitely pockets and areas where you can still invest in real estate, and it's a good investment into the future. So we look at that too, and we help clients to buy real estate often.
Beau Wirick: We love real estate.
Stacey McKinnon: We do.
Beau Wirick: It's just not all real estate is created equal at this point.
Stacey McKinnon: Exactly. And so that's a good example of maybe a Modearn client comes to us. They feel like they have a good strategy. But when we dig into the numbers and we do the analysis for them, it's interesting to see that not all real estate is created equal.
Beau Wirick: And especially if it's complex. But when it's like I've inherited this real estate, there's like this emotional attachment to my parents never sell this property is what they you know.
Stacey McKinnon: Yeah. So much. My grandma always say that never sell the property but. Right. They bought it in the 1970s for $40,000. So that's different than the current value at 2 million. And you know, we as modern people are already faced with this dilemma of life being so expensive. Now we inherit this piece of real estate. Property taxes go out maintaining the property goes up. Like that's. One other challenge I see often is you get this piece of real estate and you see the monthly checks coming in, but then all of a sudden you forgot that that roof needs to be redone and those windows are not compliant anymore, and you need to redo the landscaping and the paint is chipping. And so all of a sudden those income numbers start decreasing because of all the maintenance that has to be done on these properties.
Beau Wirick: And you're getting the 2 a.m. phone calls from the tenant. This is not passive investing.
Stacey McKinnon: No no no no
Beau Wirick: Its very active . So those conversations are really interesting.
And I think having that person who's who doesn't have the emotion involved in the real estate purchase is really helpful. And then we have the the opposite. Someone's in a house that they don't want to live in anymore.
Stacey McKinnon: Yeah.
Beau Wirick: I was like, I don't want to live here. But I feel like if I sell it, I'm giving up this, this piece of real estate
Stacey McKinnon: Or low mortgage
Beau Wirick: or ya a low mortgage rate. Yeah, that's another one. Yeah. But it's like I really want to, like, live in this different city or I actually want to jump around for the next few years and for that client, oftentimes renting is a more appropriate situation than owning this real estate that you really don't want to own anymore. So we'll do the same exact calculation just on the other side. As long as you rent something that's below this price, you're actually not losing money. Well, we've taken everything into consent.
Stacey McKinnon: It's very surprising to people too, because again, often times our parents say the American dream is that you own real estate. And that's not always the financially wise thing to do, which is an interesting analysis. But to your point, it all depends on the client. It's customized. This is not Googleable advice, right? You actually have to sit down and have a conversation and weigh these pros and cons to actually get to the answer.
Beau Wirick: Yeah, I can't ask ChatGPT how do I feel about where I live? do I like living where I live? Like, do I want to move?
Stacey McKinnon: And what are the implications of that? And how will I feel if I don't own real estate? Will it be freeing? Meaning, I'll have more money in the bank, so I'll have more freedom for lifestyle choices? Or will it actually feel like I'm doing something wrong by not owning real estate and not paying an emotional feeling will be too much for me. These are real conversations that we're having.
Beau Wirick: Yeah, and we're talking about massive price points. You're selling or buying real estate for 1 or $2 million. I mean, this is a huge decision, paying a little bit of money to have an advisor on your side to help you make the right decision. It's priceless, in my opinion.
Stacey McKinnon: Totally makes sense. When we hit on real estate the second category you shared was investments. So share with me a little bit about how you've been working with clients through some of their investment dilemmas, or kind of making a portfolio that really is a reflection of their values?
Beau Wirick: Yeah. So a lot of the times we'll have clients come to us who have a lot of assets that we really can't manage, right? They have their own business, they have their 401K plan, they've got RSU's. And in a, you know, a tech company stock, you know, this isn't stuff that we tend to manage. But we can still help them with their investment decisions. And so let's use the example of someone who works for a tech company. And they have a lot of restricted stock units that they have built up over their tenure working for that company.
If you sell those RSU's, you're going to pay a lot of, you know, capital gains tax. And if you live in California, there's a pretty big tax bill. So you don't want to necessarily sell those in order to just diversify away. But at the same time that clients like, I don't know with the how the market's been moving lately, the stock has been down 20-30. You know, 35%. It's really scary if a lot of your net worth is in one company. And so there's different strategies that we've helped clients with in order to get them as far away from that concentration as possible without, like incurring a big tax bill. So one of those strategies is as you get new RSU's that get paid to you, you sell them because that's the exact same as getting paid cash.
There's no tax consequence for that. But if you also have an employee stock purchasing plan, then you can purchase the stock from there and therefore you're getting like a 15% discount. That's usually what it is. And so if you do both of those things, then you are getting the best tax situation as you can. And kind of diversifying away from that, that stock, you can take that RSU money and go invest in something else.
Stacey McKinnon: Yeah interesting. And that's a little bit more of like a complex strategy. But we can work it out and basically combine that with everything else happening in their financial life and make sure it's not just a smart strategy for smart strategy sake, but also makes sense for the rest of their life.
Beau Wirick: 100%, because they might not just have that one goal of diversifying away from that stock, they could have another goal of like saving for education or saving up for a mortgage or, you know, saving up for a vacation.
And so if you need liquidity, you have to do that strategy, even if it's not for the sake of diversification. There's so many different questions that we have to ask the client before we give them a recommendation like that.
Stacey McKinnon: Yeah, I'm on the investment side too. Sometimes I find that some decisions that modern clients have to make are a little bit complicated in how to afford life today, but maybe one of the partners wants to stay home with the kids, and so they need a way to invest where they can draw a passive income to help supplement the fact that their spouse is no longer working to help raise the kids when they're really young.
That's also an interesting investment strategy that we've employed for a lot of clients,
Beau Wirick: Right? So let's use that example of that, of you're working for a tech company. Maybe that stock pays a little dividend, it pays you a little income. But it's like 0.5%. Right. And so that's a great stock maybe to have for the long term for growth.
But if you need income from your investments to replace the salary well you need to really invest in something that's paying you a higher yield. You know. So a lot of our strategies, like loans that are backed by real assets, those are the right types of strategies for that situation. And so you never know, like what someone needs is going to dictate what their portfolio looks like.
Stacey McKinnon: Totally. Again, not Googleable.
Beau Wirick: It will keep on hammering that hole right.
Stacey McKinnon: Okay. So the third category that you mentioned is education planning, which could include private school planning or college planning. You know, what's really interesting is that ten years ago this conversation was only about college planning. But the evolution of private school planning has become a big topic of conversation for Modearn clients. Can you just share a few examples of maybe how you've helped clients through education planning.
Beau Wirick: 100%? So this one I think is harder for people to grasp than I even give it credit for. You know, if we're living in this world and we're financial planners, it's really easy for us to kind of get to the right answer. But, so here's the thing with education planning. One is you have such a shorter time to invest money if your kid is, say, is ten years old and they're going to go to college at age 18, that's an eight year window between starting the investment and needing to pull from the investment. That's not a long time for the stock market. The stock market could do a lot in that eight year period, and so that alone makes it a different consideration of is it appropriate to to invest for education? If you're talking about elementary school, it's that same problem. Let's say your kid's one and you're going to start using it for private school at age ten. Then you have a really short amount of time.
You could actually lose money on the investments over the next ten years, right? Whereas when you invest for retirement, you're usually looking at a 30-40 year time horizon where it's like it's almost impossible for you to not make money in the stock market over 30 years. And so that's the first place where we have to kind of educate clients of when you're talking about education planning, you are dealing with a different problem to solve.
Stacey McKinnon: Yeah, very short, a shorter time horizon.
Beau Wirick: Shorter time. Right.
Stacey McKinnon: Like if you would have been unlucky, if you would have done this in 2000 and needed the money in 2010, that was the last decade. Stocks basically mean nothing over that ten year period.
Beau Wirick: That's exactly right.
Stacey McKinnon: You've only had what you put in. I mean, that's a dangerous place to be in, right?
Beau Wirick: Yeah, exactly. And so if you are really loading up a 529 for your kid and that doesn't make any money, well, this is one of the thing. You don't get a tax deduction for putting it in a 529. You only get a tax break on the earnings. So if there's no growth over the next eight years, you're really not getting any sort of benefit.
So let's compare that to your own retirement accounts. A lot of the time. I'll have a client who is not maxing out their own retirement accounts, but they're putting a lot of money into their kids. 529 usually, usually that's not the right decision. I usually tell people it's better to like, you're on a plane, put on your own mask first before putting on a mask for your kid. You want to make sure that you're not a burden on your child when you retire. That's more important than them having, you know, getting to go to USC, which I think is very cool.
Stacey McKinnon: Yeah. You think that.
Beau Wirick: All right. So that's one thing. And then also there's a lot of clients who are in our age range who are having kids later.
Stacey McKinnon: Yeah.
Beau Wirick: And so like I'll use my cellphone as an example. I'm turning 40 next year and I'm having my first kid this year. And so I'm pretty old. Like I'm a pretty old dad. Well, one of the things that's cool about that is I have a Roth IRA, a Roth 401 K by the time I'm 59.5, my kid will be like a sophomore in college.
Stacey McKinnon: Yeah.
Beau Wirick: So a Roth IRA and a Roth for one K, actually, exactly the same as a 529.
Stacey McKinnon: It's a good strategy
Beau Wirick: And so if I'm not maxing out my Roth 401 K, which I can use for anything, not just education, I'm not going to touch a 529 until that is totally satisfied.
Stacey McKinnon: Interesting.
Beau Wirick: Yeah. And so that's something that there's not a lot of people think about. A 529 is only used for education, and you get penalized if you don't use it. A Roth if you're an older parent, you can really use it for anything you want. Say your kid gets a scholarship. Yeah, yeah. You don't need you don't need education planning that stuff.
Stacey McKinnon: Yeah. If you can compound the gross tax free, then it makes sense to do it.
Beau Wirick: Makes sense.
And especially if you can access it at the right age. And if they don't need it, then it just continues to grow. Yeah. Tax free.
Stacey McKinnon: Totally. I mean these dynamics are so challenging. And sometimes I even work through with clients. Should they fund half of college in the 529, the other half through a taxable savings account where you're not getting the tax free growth, but you have a dedicated bucket of money. But if the kids don't go to school, they get a scholarship, they get a state grant, whatever it is you haven't, like put all the money into a 529. Right. And so the this is not a black and white discussion again.
Beau Wirick: So it's very personal.
Stacey McKinnon: Yeah. Very personalized. Yeah I know these are really important conversations that we're having with a lot of our clients.
Beau Wirick: Yeah. And there are a lot a lot of them are mathematical conversations. Right. There's a problem to be solved. And we can get to the answer by doing the math right. And we help them do the math. But there's a whole other layer to this, which is the emotional side of things. And oftentimes it's not just a financial decision, it's also an emotional decision.
So I know that you are, I think, an expert on this, like getting to the real issue behind the issue. And so tell us some stories about how you've helped Modearn clients with their emotional financial decisions.
Stacey McKinnon: Oh yes. I usually ask 2 to 3 to 5 to 7 questions. I don't get to like the meat of it. I would say that one of the things about Modearn that I feel is maybe surprising, something we didn't anticipate, but it's been a benefit, is the role that we play as referee. Oftentimes especially couples are in this situation where let's say they got married in their mid 20s. Now it's ten years later. For ten years, they've made all of the financial decisions together. So it's become group think. It's become like and sometimes combative. Right. Like I believe one way. You believe another way. And so we're missing each other in the discussion. And so we make no decision because it's too hard to make a decision when like one of us has to win and one of us has to lose. And so I think one of the most important roles we play is the role of referee.
The role of like, let's go through both the pros and cons and the dynamics that we're faced with in making financial decisions. And let's say, hey, I hear you at this point and this point that I hear you in this point. And can we find, meaning in the middle that both satisfies the two different points of view? Because the reality is most people grow up in different situations. Maybe somebody grew up with a wealthy family and they have an abundance mindset. Maybe somebody grew up without much. And so they have a scarcity mindset. Us helping to marry these things together to get people on the same page so they feel really confident in the decisions are making. I think that's been a surprising benefit for a lot of clients.
Beau Wirick: Yeah, I mean, we're not therapists now. Sometimes we are. All right. Like just having that third person's point of view to help translate.
Stacey McKinnon: Exactly.
Beau Wirick: I heard what she just said. Did you hear what she just said? You know, it just helps facilitate the conversation.
Stacey McKinnon: And repeating back and things like that. So I think that's really helpful. And the second thing I would say more from the investment viewpoint is like, I think we're helping our clients prepare for a recession. Something that I often reflect on is that if you are in your late 20s, the last time a recession happened, you were like graduating elementary school. And for us, we were graduating college when the last recession hit, which was a little bit hard on us from a job market standpoint. But some of us still had our parents to help us and protect us. A lot of us haven't really felt what a recession feels like, and I think one of the most important roles we play is just helping people to build an investment strategy that isn't. I got this stock tip from my friend, and so I'm investing in it.
But rather what are my values? What are my dreams? Sort of my goals? And how do I protect myself from political unrest? National security, inflation, interest rates, all of these big things that are out of our control. How do we bring more control to an investment strategy? And I think that that's a big benefit as well.
Beau Wirick: I think you hit that on the head. It's like our entire adult life post great financial crisis. Every single time there's been something that's been like a hint that's gone wrong. Yeah. The Federal Reserve steps in and prints a bunch of money. The government steps in and sends people checks. And so our generation is kind of gotten to this point where we're like, someone will say, if the cavalry's all this like, you know, I'm not going to derisk my portfolio because I've been rewarded for the risks that I've taken.
But when that U-turns, at some point it'll be pretty painful. And so we're trying to prepare people like you haven't seen this. Yeah. Not it. Right.
Stacey McKinnon: Totally. Totally could happen. Yeah. It's a good role that we play. Like helping people to both scale their lives to live bigger lives, to, maximize their earning potential, whether that's through their jobs or their investments or just their financial planning, but then also to protect them from some challenging times that could happen in the future. And so how do we like layer in that safety net so that those big things that they want to achieve or actually achievable.
100%.
Stacey McKinnon: All right. So it's time to play my favorite game. Our favorite game. Our favorite game of the episode this or that, where we'll ask each other questions. And you know, you got to like you got to pick one, which it's always hard.
So we both would consider ourselves Modearn clients. Would you say at this point in life, you just said that you're about to have a child. They're more currently focused. Our future me focus.
Beau Wirick: What's the right answer? Is my wife watching? I so truthfully, I mean, it's kind of obvious, but yeah, so much more future me focus now that I have like a dependent on the way I care so much less about, say, traveling to Europe and so much more about just saving for retirement.
Stacey McKinnon: Yeah, yeah
Beau Wirick: it's amazing how my mind has shifted. Whereas literally five years ago I probably would have answered, like, I'll take less pay for the sake of like two months of vacation every year to be able to travel the world. No, no, not anymore. So yeah, definitely my mindset, my mindset has shifted
Stacey McKinnon: Like scale and grow because you got more people to take care of.
Beau Wirick: Yeah, yeah. Well and you know education we already talked about okay. You're your first question. Speaking of travel, let's say that you're given the opportunity to move to New York. You live in California. Now, just as a reminder, but it's you get a 50% raise in compensation. Okay? But you but you have to leave your friends. You have to sell your properties. You have to, like, start a whole new life. Is that the number? Like, where's the threshold for you to, like, up, uproot and move to, say, like New York City?
Stacey McKinnon: Yeah, I think the answer is just going to be no. Just no hard no. Yeah. Okay. I have a I have a puppy. I don't want her paws touching the streets. It's a whole thing. Totally. Yeah, I, I wasn't I find New York to be a very beautiful place to visit. And I find it to be, like a very fascinating environment where for so many people, that's the number one place that they lost the most, that they would choose New York over anything. Oftentimes I think this comes down to like where you were raised. And remember earlier, at the beginning I shared that I'm from Lake Tahoe, which is like mountains and rivers and streams and lakes and paddleboarding and bike riding. And I just think that maybe it's the opposite of New York. And I find that it's really fascinating when you as you grow up, sometimes you revert back to the beginning.
And so I think that I probably wouldn't survive very long in the opposite of Tahoe.
Beau Wirick: Do you feel like when you were younger and someone gave you that same offers like, hey, 50% more pay, here's an adventure.
Stacey McKinnon: I probably would have taken it. Yeah, yeah, yeah. It's just interesting and fascinating how life changes over time.
Beau Wirick: Yeah. Oh, that's there's no amount of money that can get you to leave.
Yeah. Yeah. Okay. Good to know.
Stacey McKinnon: All right. So you mentioned earlier when you think about investing and investing in new home specifically that there is a dynamic of looking at renting versus owning for you personally and I we've spoken about this before. What is your opinion on renting versus owning for where you are today?
Beau Wirick: I think I, I so fall into that category of like, I'm a renter right now. Hi, my name is Beau Wirick, I rent, but I fall into that renter status and I've had a lot of like disappointment around that just because things in life didn't work out, blah blah blah. And as I've gotten older, I've actually come to a place where I actually appreciate it. Yeah, I like being able to call the landlord like, hey, something's wrong. I like the ability to like, hey, anytime that we want to go someplace else, we can we can move bigger. We can move smaller. I like the flexibility a lot, so I've grown to appreciate that. Maybe that's my brain just kind of like justifying things. But as interest rates and house prices have gone up, I check Redfin Weekly at this point to see if I'll change my mind and to buy something.
And the answer is every single week. No, no, no, I'm swiping left on owning every single time. And it's because it's too expensive. The math does not math for for me at least. Maybe someday it will. But not right now.
Stacey McKinnon: I mean, I think there's a lot of hidden cost that people don't realize, right? I have a home in Tahoe, and just last year my insurance dropped me because when I bought the home, the electrical panel was outdated and I did not check the electrical panel and know if it was outdated or not.
Apparently insurance companies were not approving this specific electrical panel. So then I just spent a lot of money to get my electrical panel upgraded. That's the simple example of these things happen and you just don't plan for them. And so I kind of think that maybe you're on to something.
Beau Wirick: Yeah. You don't need insurance in Tahoe. There's no fires or snow that can probably damage your property. Yeah. It's crazy. The expense of homeownership has just gone up astronomically lately.
Stacey McKinnon: Totally.
Beau Wirick: Okay. Speaking of real estate, this is your last question. You are given an inheritance. Okay, let's call it, I don't know, $2 million. Oh, wow. All right. Pretty good inheritance.
Stacey McKinnon: This is exciting.
Beau Wirick: Yeah. You have two choices. You can take that $2 million and you can buy a property with it. Or you can buy one property, And not in New York. Obviously. So you buy up property with it, or you can invest it in different investments like, you know, marketable securities of some sort is my property.
Stacey McKinnon: Does my property get to be on the lake in Tahoe?
Beau Wirick: $2 million gets $2 million. I mean, where can you buy that?
Stacey McKinnon: I probably am investing. I probably, want to like, build and grow that well, so I have the flexibility to make other decisions. I think one of the things about real estate that always kind of gets me is just, it's more locked up than we think. We think about building equity in our homes, and that makes us feel good. But to actually make the decision to get any of that equity is a hard, hard decision.
And so I think I probably would rather invest the money and have the flexibility to do a lot of different things with it, as opposed to lock it up in one property.
Beau Wirick: Not to keep on, just like harping on this, but it's like when you are buying a property, cash properties really only go up by like 4 or 5% per year. It's actually the debt that you have on the property that usually makes the investing in real estate go up much faster. And so you buy it cash. It's not that great of an investment usually. And so right now you look at that you're probably going to get some better returns elsewhere. Most likely I think so yeah for sure okay I agree with your decisions and I appreciate you not leaving us and moving to New York.
We're happy about that.
Stacey McKinnon: Well, thank you for being my Modearn advisor during this conversation.
Beau Wirick: Personalized everything.
Stacey McKinnon: Exactly. Yeah, sure. Yeah. You put the stamp of approval on my decisions.
Beau Wirick: Approval? Stamp. Oh, well, that's a great conversation. And honestly, I feel like that's a good example of when we meet with Modearn clients. We really are trying to have this long of a conversation. And for us to get this much time with a client, we can't have 800 clients. Stacey. And so what we're trying to do is make sure that we set aside enough time, set aside the resources to make sure that every single Modearn client gets the expertise and the time that they need. They've got our cell phone numbers. They can talk to us whenever they want to. So that's what we're passionate about.
Stacey McKinnon: Giving people partnership because it's easier to make good decisions when you have someone to call.
Beau Wirick: Absolutely. Wow.