October 2026
Featuring
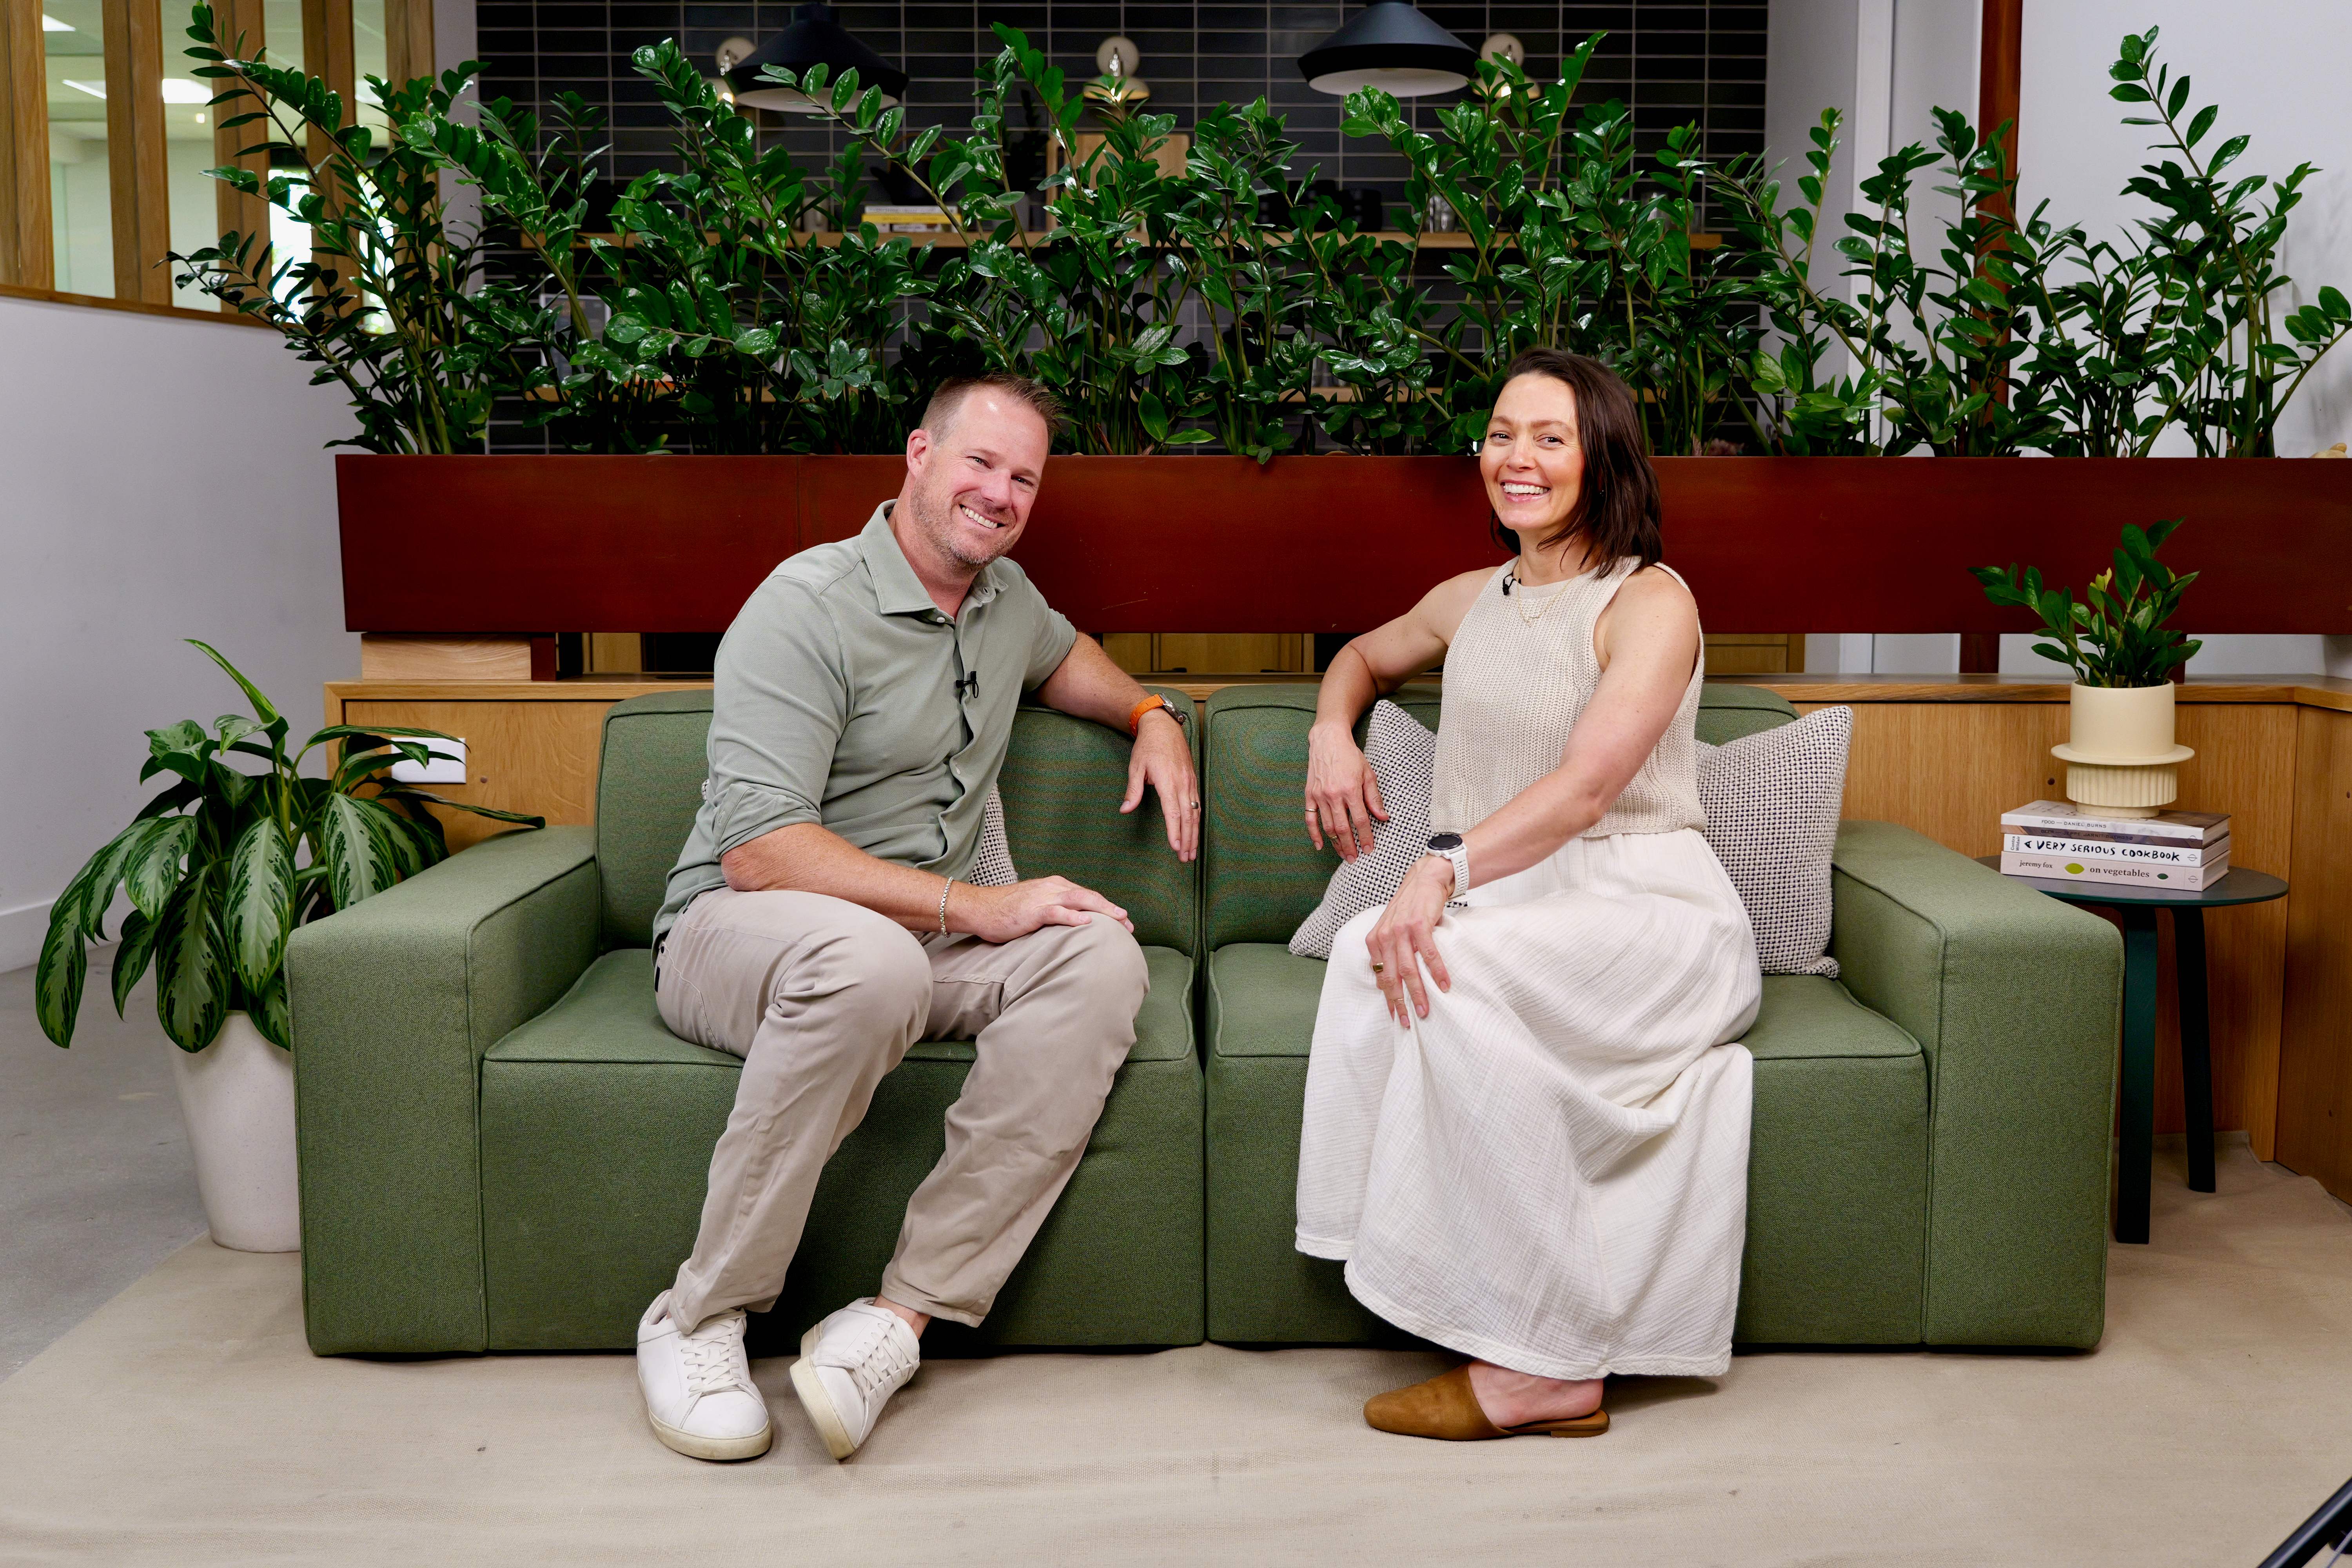
Kristin Dillon, Wealth Advisor
Most people who want to change careers don’t quit because they’re not ready emotionally. They stay because they’re not sure they can afford to leave. In this episode of Couchside Conversations, Wealth Advisors Kevin Rex and Kristin Dillon speak from experience: Kevin left a successful medical sales career with a newborn and a second on the way to join Morton Wealth. Kristin left hairdressing after a medical emergency forced a decision she’d been putting off for years. Together they work through the financial and emotional calculus of making the leap, what you actually need in place before you go, and why the better question might not be whether you can afford to change, but whether you can afford not to.
The question isn’t whether you can afford to change. It’s whether you can afford not to.
Time is the one resource you can’t replenish. Kristin waited until a medical emergency forced her hand. Kevin’s wife had to push him to move before he’d talked himself out of it. Both look back grateful, and both wished they’d started the process earlier. Staying in a career that isn’t working has costs too, and those costs tend to be invisible until they’re not.
You’re not starting over. You’re starting from somewhere.
Every year of experience, every relationship, every skill developed in a previous career comes with you. Kevin’s medical sales background, where he coordinated complex teams and got orthopedic surgeons the answers they needed, turned out to be exactly what financial advising required. Kristin’s decade as a hairstylist, where she held space for people and listened with real attention, became the foundation of her practice. The career changes that felt like starting over were really just translations.
Fulfillment drives the decision. The finances are the framework.
Neither Kevin nor Kristin made their career change primarily for money. Both took pay cuts. Both describe the change as one of the best decisions they’ve ever made. The pattern they’ve seen with clients holds: more money does not produce more happiness. What produces satisfaction is work that aligns with your values, uses your strengths, and gives you the flexibility to show up for the rest of your life.
Debt is the enemy of a career change.
High-interest debt takes away the one thing a career change requires most: flexibility. Kevin’s advice is to use the runway period before a leap to eliminate high-interest obligations so that a reduced income during the transition doesn’t spiral. This doesn’t mean paying off your mortgage. It means making sure no single fixed payment can sink you if income drops.
Build the plan, then take the leap. But don’t let the plan become the excuse.
Kevin closes with the point both advisors land on: planning is essential, but over-planning becomes procrastination in disguise. Once you know your non-negotiable monthly expenses, have some runway saved, understand the income trajectory of the new path, and have a safety net you can identify, you have enough to go. The right moment is rarely perfect. At some point you have to rip the band-aid.
“When you get up every day and you’re just excited to go to work, and the challenges and obstacles that you face aren’t depleting, but actually exciting, I think that’s when real success actually happens.” — Kristin Dillon
0:00 Intro: for everyone thinking about a career change but scared of what it costs
1:01 Two career changers at Morton Wealth, starting with their stories
1:45 Kristin’s story: hairdressing, a medical emergency, and the leap she’d been avoiding
3:17 Kevin’s story: medical sales, a wife’s push, and leaving something he loved for something better
4:46 Can you afford not to? Time is finite and staying has costs too
9:13 You’re not starting over: why every career translates more than you think
12:13 The financial preparation: Kristin’s low-expense approach vs. Kevin’s pay cut with a newborn
17:13 Is a career change emotional or financial? Both say emotional comes first
20:50 Vera Wang, Rich Roll, and what following a calling actually produces
21:06 The practical checklist: fulfillment, earning trajectory, and your safety net
23:31 Debt, health insurance, and the hidden costs people forget to factor in
27:01 This or That: leap now or wait, career change at 35 vs. 45, one year of runway or two
These are the questions people seriously considering a career change are genuinely asking. The full conversation, including both hosts’ personal stories, is available in the transcript further down the page.
Can I actually afford to change careers?
The short answer depends on three things: what your non-negotiable monthly expenses are, how much runway you have saved, and what the realistic income trajectory of the new path looks like over one to five years. Most people focus only on the immediate income gap and miss the longer-term picture. Kevin took a pay cut when he joined Morton Wealth. Looking at the trajectory of what that career would become, not the starting salary, was what made the math work. The question to ask is not whether you can afford the first six months. It’s whether the path you’re moving toward can get you where you want to be in five or ten years.
How much should I save before leaving my job to change careers?
Kevin and Kristin land on roughly one year of mandatory expenses, meaning not your current lifestyle budget but your stripped-down, non-negotiable monthly obligations, as the minimum baseline. For people starting a business rather than joining an existing employer, two years is more appropriate, since the early years of building something typically require reinvesting most of what comes in. The more important preparation step that often gets skipped: reducing high-interest debt before you make the move. Debt payments are fixed. Income during a transition is not. That mismatch is where career changes fail financially.
Is it too late to change careers in my 40s?
Not according to the evidence Kevin and Kristin cite. Vera Wang pivoted to wedding dress design and became the defining name in the industry. Rich Roll left a successful legal career in his 40s and built a more fulfilling and more successful life doing it. Martha Stewart didn’t become a household name until her 40s. The pattern is consistent: people who follow a genuine calling, even late, tend to produce work that reflects the accumulated experience of everything that came before. What you bring to a new field at 45 is categorically different from what you brought to your first career at 22.
What are the biggest financial mistakes people make when changing careers?
The most common ones Kevin and Kristin see: underestimating monthly expenses by only counting obvious bills and missing things like health insurance, which can be a significant cost when it’s no longer employer-subsidized. Not accounting for the loss of benefits like equity, vesting schedules, or paid time off that don’t appear in a salary comparison. Carrying high-interest debt into a lower-income period, which eliminates flexibility exactly when you need it most. And over-planning to the point of never actually going, which is its own kind of costly mistake.
How do I know if I’m changing careers for the right reasons?
Kevin’s framing is useful here: if you’re making the move primarily to earn more money, you’ll probably keep moving. More money doesn’t produce more satisfaction, and they’ve seen this pattern across thousands of Morton Wealth clients. The career changes that stick are the ones driven by a pull toward something, not just a push away from what isn’t working. Kristin’s test was a list she wrote years earlier describing her ideal career. When she looked back at it after joining Morton, it matched almost exactly. If you can’t articulate what you’re moving toward, the move may be premature.
Does my previous career experience transfer to a completely new field?
Almost always more than you think. Kevin came from medical sales, a world of coordinating complex teams, managing relationships with high-stakes experts, and finding the right resource for the right problem. That turned out to be exactly what financial advising required. Kristin spent a decade as a hairstylist developing the ability to hold space for people, listen with real attention, and connect across a wide range of human experience. Those are the skills that make a great advisor. The title and the industry changed. The core competency translated directly.
Should I tell my employer I’m thinking of leaving?
Kevin’s answer: wait until you’re ready to go. The risk of disclosing too early is real. Employers who know a departure is coming sometimes accelerate it on their own terms, not yours. The practical guidance is to complete your preparation quietly, give your employer enough notice to make a genuine transition possible, but don’t hand over leverage before you need to. The exception is if you’re at a firm where leadership is known to handle these situations graciously. Know your environment.
This episode is for the person who's been thinking about a change longer than they’d like to admit. The career is fine. The salary is fine. The path is clear. And none of it feels like enough. That feeling has a financial dimension that most people haven’t fully mapped, and an emotional dimension they’ve been pushing down because the timing never seems right.
This episode is especially relevant for:
At Morton Wealth, these conversations happen constantly. A career change is one of the biggest financial decisions a person can make, and it almost never gets the same planning attention as a home purchase or a retirement date.
Watch previous episodes here:
How Do You Build a Portfolio That’s Ready for Uncertainty? | Morton Wealth
Financial Planner or DIY: How Do You Know Which One Is Right for You? | Morton Wealth
DISCLOSURES
Information presented herein is for discussion and illustrative purposes only and is not intended to constitute financial advice. The views and opinions expressed by the speakers are as of the date of the recording and are subject to change. These views are not intended as a recommendation to buy or sell any securities, and should not be relied on as financial, tax, or legal advice. You should consult with your finance professional, accountant, or tax professional before implementing any transactions or strategies concerning your finances.