October 2026
Featuring
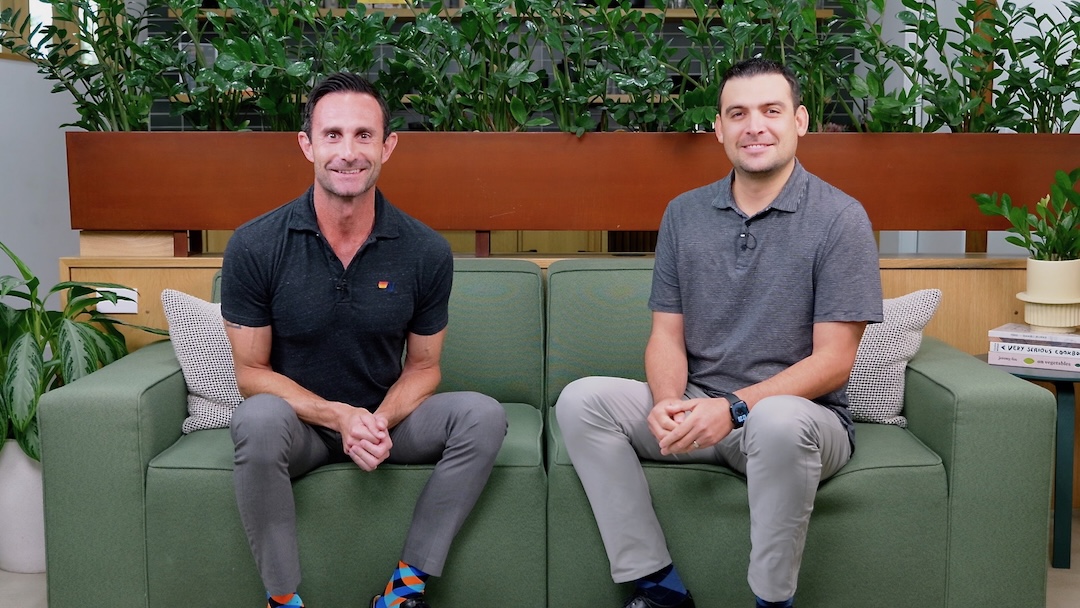
Most people who feel financially behind have never stopped to ask what they’re behind on. In this episode of Couchside Conversations, Wealth Advisors Mike Rudow and Ian Rennick dig into one of the most common yet least examined feelings their clients bring to them: the sense that everyone else is further along.
They work through where that feeling comes from, why the benchmarks driving it are almost always the wrong ones, and what it looks like to build a plan around your own goals instead of someone else’s highlight reel.
You’re probably not as far behind as you think.
Ian’s opening client story makes this concrete: a client so convinced he was behind that he was taking aggressive options plays to close the gap, without ever having established a baseline. When they actually ran the numbers, the client was further along than he realized and able to redirect his energy toward what he actually wanted: more time with family and the freedom to work by choice, not necessity. The feeling of being behind and the reality of being behind are often very different things.
The benchmark you’re using is almost certainly the wrong one.
Comparisons only mean something when they’re relevant. Comparing your portfolio return to the S&P 500 when your goals, timeline, and risk tolerance are nothing like the index is the same error as comparing your life to an Instagram influencer who is paid to present a curated version of it. Mike’s point is direct: we are a society of comparison, and most of the comparisons we make are not relevant to what we’re actually trying to accomplish.
Start with your big rocks, not your balance sheet.
Before Mike looks at whether a client is ahead or behind, he asks what their non-negotiables are: the things they cannot compromise on. Being present as a parent, having freedom of time, accelerating in a career, maintaining a certain quality of life. Those big rocks define what the financial plan is actually in service of. Without that foundation, any benchmark is arbitrary.
In a crisis, control what you can and release what you can’t.
When the feeling of being behind is driven by something real, a divorce, a job loss, a health crisis, the approach changes. Mike’s framework is to identify the variables within a client’s control and focus entirely on those. You can’t control the markets. You can control whether you’re making retirement contributions, building an emergency fund, showing up well at work, and taking care of yourself. That focus naturally reduces anxiety and starts rebuilding momentum.
Celebrate small wins. The bar is always going to move.
One of the patterns both advisors see repeatedly: someone pays off a significant debt, and instead of acknowledging it, they immediately feel behind on the next thing. The bar moving is not a problem. It’s part of staying motivated. The problem is skipping the acknowledgment entirely. Small wins compound in confidence the same way dollars compound in a portfolio, and the habit of recognizing progress is what makes the next stretch sustainable.
1:03 Introduction: the feeling of being behind, why it’s so common, and what today’s episode is for
2:10 Ian’s client story: covered call options, buildings in California, and the baseline that changed everything
5:48 Mike’s framework: start with the big rocks before looking at the numbers
9:07 Comparison as a society: why the benchmarks we choose are almost always the wrong ones
11:12 Celebrating small wins: why people skip it and why it matters
13:46 When being behind is real: divorce, job loss, health crisis, and the control framework
18:14 Age and the feeling of being behind: 25 vs. 65 are completely different conversations
19:27 Ian’s story: from fitness coaching to financial advising, and how the definition of success changed
24:25 Balancing experiences now with building for later: the young client dilemma
26:05 Do you actually need the highest return? Matching risk to the life you described
28:53 This or That: net worth to the dollar vs. general sense; experiences vs. retirement savings; feel ahead of peers vs. aligned to your own goals
These are the questions people wrestling with financial comparison and the feeling of being behind are genuinely asking. The full conversation is available in the transcript further down the page.
Why do I always feel financially behind?
Usually because the benchmark you’re measuring yourself against isn’t actually yours. It might be a number a parent instilled early on, a figure you heard on a podcast, a lifestyle you saw on Instagram, or a peer you’ve decided represents what success looks like. None of those benchmarks account for your income, your expenses, your goals, your timeline, or what you actually want your life to look like. The feeling of being behind is real. What’s much less certain is whether the benchmark producing it has any relevance to your actual situation.
How do I know if I’m actually behind financially, or just comparing myself to the wrong things?
The only way to know is to establish a real baseline. Ian’s client story illustrates this clearly: a man so convinced he was behind that he was making aggressive options trades to close a gap he’d never actually measured. When they built a financial plan together, ran the numbers, and looked at all of his assets including some underperforming commercial properties, he was further along than he’d assumed and able to redirect his strategy entirely. The starting point is always: where am I right now, and what do I actually need to get to where I want to go? Everything else is noise.
What should I do first if I feel like I’m falling behind financially?
Mike’s answer: before you look at a single number, identify your big rocks. The non-negotiables. The things you cannot compromise on. Being present for your family. Freedom of time. A certain quality of life. Career progression. Those big rocks define what the financial plan is actually in service of. Once you know what you’re building toward, you can assess whether you’re behind on something that actually matters to you, or whether you’ve been measuring yourself against something you don’t actually want.
How do I stop comparing my finances to other people’s?
Mike makes an observation that’s worth sitting with: when we compare ourselves to others, we choose who we compare to. And almost always, we choose the peak. The influencer, the celebrity, the neighbor whose highlight reel we see but whose full financial picture we don’t. Comparisons work when they’re relevant. Comparing your portfolio return to the S&P 500 when your goals and timeline are nothing like the index is not a useful comparison. Neither is comparing your life to someone whose job is to make their life look aspirational. The redirect is internal: what are you trying to accomplish, for yourself and your family, and are you making progress toward that?
What does feeling financially behind look like at different ages?
Very different things, according to both hosts. At 25, the feeling of being behind is usually driven by social comparison and the difficulty of imagining a life 20 or 30 years out. The goals are abstract, the timeline is long, and the pull toward experiences now is strong and reasonable. At 55 or 65, the picture is much clearer: you know what you want retirement to look like, you have a much better sense of what it costs, and the timeline is real. The advice changes accordingly. For younger clients, the focus is on building good habits and capturing compound time without sacrificing the experiences that make the present meaningful. For clients closer to retirement, the focus is on closing specific gaps with a specific plan.
How do I handle feeling financially behind after a major life event like a divorce or job loss?
Mike’s framework for crisis situations is built around a single question: what can I control? You cannot control what the markets do, what your former spouse does, or how long a job search takes. You can control whether you’re making retirement contributions, building an emergency fund, showing up well at work, taking care of your physical health, and making your financial decisions thoughtfully rather than reactively. Focusing on the controllable variables does two things: it reduces anxiety, because most anxiety comes from fixating on things beyond our control, and it starts rebuilding momentum in a direction that actually matters.
Should I focus on experiences now or save more for later?
Both, according to Ian and Mike, though the balance shifts with age. The mistake younger people often make is treating this as an either/or decision. Putting all your money into experiences and ignoring savings entirely means waking up ten years from now wondering how everyone else accumulated what they did. But saving so aggressively that you miss the experiences only available when you’re young and healthy is its own kind of loss. The answer is a plan that explicitly makes room for both, not as a compromise but as a deliberate allocation, because time is the one resource compound interest cannot replace.
This episode is for the person who has been doing the right things, contributing to a 401(k), keeping expenses reasonable, avoiding major mistakes, and still has a nagging sense that they should be further along. That feeling is more common than almost anyone admits, and it almost never reflects the actual financial picture.
This episode is especially relevant for:
At Morton Wealth, the first thing we do is establish a real baseline. Not a benchmark from a podcast or a number from a parent, but a clear picture of where you actually are and what you actually need.
Watch relevant content here:
I Want to Change Careers But Can I Afford To? What to Know Before You Leap
DISCLOSURES
Information presented herein is for discussion and illustrative purposes only and is not intended to constitute financial advice. The views and opinions expressed by the speakers are as of the date of the recording and are subject to change. These views are not intended as a recommendation to buy or sell any securities, and should not be relied on as financial, tax, or legal advice. You should consult with your finance professional, accountant, or tax professional before implementing any transactions or strategies concerning your finances.