September 2026
Featuring
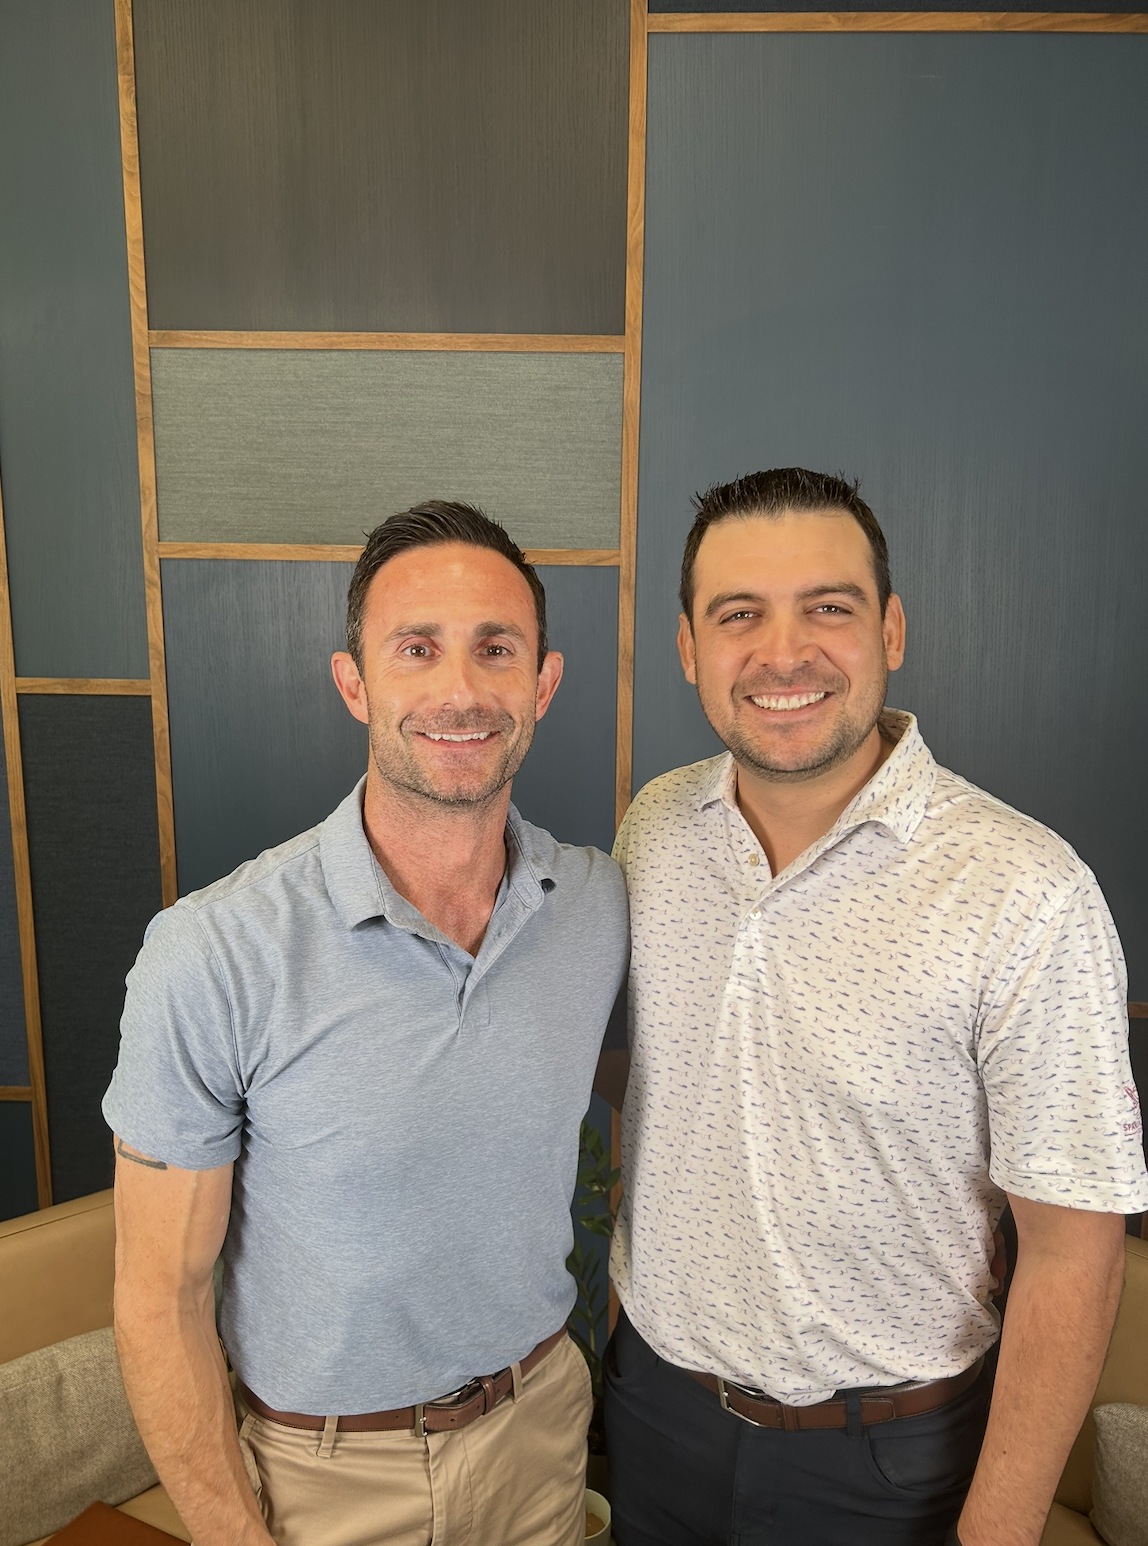
Mike Rudow, Wealth Advisor and Partner, Morton Wealth
Ian Rennick, Wealth Advisor, Morton Wealth
You saved into your 401 (k) for decades, reduced your taxes every year you could, and watched the balance grow. But the IRS doesn’t retire when you do.
Every dollar you pull from that account in retirement is ordinary income, and if it is your only account, you could end up in the same tax bracket you were in when you were working, or higher.
In this episode of Financial Commute, Wealth Advisors Ian Rennick and Mike Rudow break down the four types of retirement accounts, why the conventional withdrawal order most people follow might be a short-sighted strategy, and what it looks like to build a customized and flexible tax-smart retirement plan before you need it.
0:00 – Intro: The IRS always gets their share, so where you pull from matters
0:49 – Welcome: Ian and Mike on retirement withdrawal strategies
1:28 – The four account types and how each one is taxed differently
4:33 – Taxes are a hug or a slug: you pay now or you pay later
5:00 – The common assumption about withdrawal order and why it's wrong
6:24 – The danger of having only one type of account going into retirement
7:18 – A real example: splitting contributions between taxable and tax-deferred accounts
8:21 – Planning for optionality: the earlier you start, the more flexibility you have
9:14 – The window between 61 and 65: a hidden opportunity to reduce your tax burden
10:55 – Roth conversions as a legacy play for the next generation
12:00 – Helping your kids buy a house or start a business: hard to do with only IRA money
13:27 – Closing takeaway: a customized, diversified strategy saves more in the long run
How do I withdraw from retirement accounts without a big tax hit?
The answer depends on which accounts you have and what your income looks like in any given year. The core principle Mike lays out is that tax efficiency in retirement is about managing your total taxable income across years, not minimizing what you pay in any single year. Pulling from a mix of traditional, Roth, and taxable accounts in a given year, rather than drawing exclusively from one bucket, gives you control over how much ordinary income appears on your return. The planning that makes this possible starts before retirement, not after.
What is the right order to withdraw from retirement accounts?
The conventional rule is taxable accounts first, then traditional IRA or 401k, then Roth last. This minimizes taxes in the current year. But Mike describes it as myopic for many people. If your traditional account keeps growing untouched while you spend down taxable assets, the future required minimum distributions from that account may push you into higher brackets in your 70s and 80s than you would have faced with a more balanced drawdown strategy earlier. The right order depends on your account balances, income sources, tax bracket, and retirement timeline.
What is a Roth conversion and when does it make sense?
A Roth conversion moves money from a traditional IRA into a Roth IRA. You pay ordinary income tax on the amount converted in the year you do it, but the money then grows tax-free and has no required minimum distributions. The best time to do a Roth conversion is when your income is temporarily low, which often happens in the years between early retirement and the start of Social Security and RMDs. Mike also notes that Roth conversions can be done as a legacy strategy even when the personal break-even point is far in the future, because inheriting a Roth account is significantly better for the next generation than inheriting a traditional IRA.
What is the early retirement tax window?
The early retirement tax window is the period between when you stop working and when Social Security income and required minimum distributions begin. During this window your taxable income may be lower than it has been at any point in your career. Mike describes it as a real opportunity: you can take distributions from traditional accounts while staying in a lower bracket, do Roth conversions at favorable rates, and realize capital gains at potentially zero or low rates. The window is temporary and planning ahead of it is what allows you to use it.
Should I put all my retirement savings into my 401k?
Not necessarily. Mike describes a scenario where splitting savings between a tax-deferred account and a taxable brokerage account produces a better long-term tax outcome than maxing the 401k alone, even though it means paying more tax in the working years. The reason is optionality: in retirement, having multiple account types gives you the ability to structure income at the tax rate you want rather than being forced to pull everything as ordinary income from a single large account. The short-term tax deduction from a 401k contribution is real, but it may not be the lifetime winner.
How does having only a 401k affect taxes in retirement?
If your only retirement savings vehicle is a traditional 401k or IRA, every dollar you withdraw in retirement is taxed as ordinary income. If the account has grown large enough to fund your lifestyle, you may be pulling out enough income to land in the same tax bracket you were in while working, or higher once you add Social Security. You also face required minimum distributions starting at age 73, which force taxable income regardless of whether you need the money. Having other account types gives you the flexibility to manage how much ordinary income shows up in any given year.
Most retirement planning conversations focus on how much to save. This episode is about what happens next, and why the decisions you make about where you save matter almost as much as how much. The tax landscape in retirement is fundamentally different from the one you navigated while working, and the people who navigate it best are the ones who built for flexibility long before they needed it.
At Morton Wealth, retirement tax strategy is not a separate conversation from the financial plan. It is embedded in every projection we run. If you are wondering which accounts to prioritize, whether a Roth conversion makes sense, or how to structure withdrawals once you stop working, that is exactly the kind of question your advisor should be helping you answer now rather than later.
Relevant Content
Finding Purpose in Your Golden Years
From Earning to Living: The Retirement Mindset Shift
Disclosures: Information presented herein is for discussion and illustrative purposes only and is not intended to constitute financial advice. The views and opinions expressed by the speakers are as of the date of the recording and are subject to change. These views are not intended as a recommendation to buy or sell any securities, and should not be relied on as financial, tax, or legal advice. You should consult with your financial professional, accountant, or tax professional before implementing any transactions or strategies concerning your finances.