October 2026
Featuring
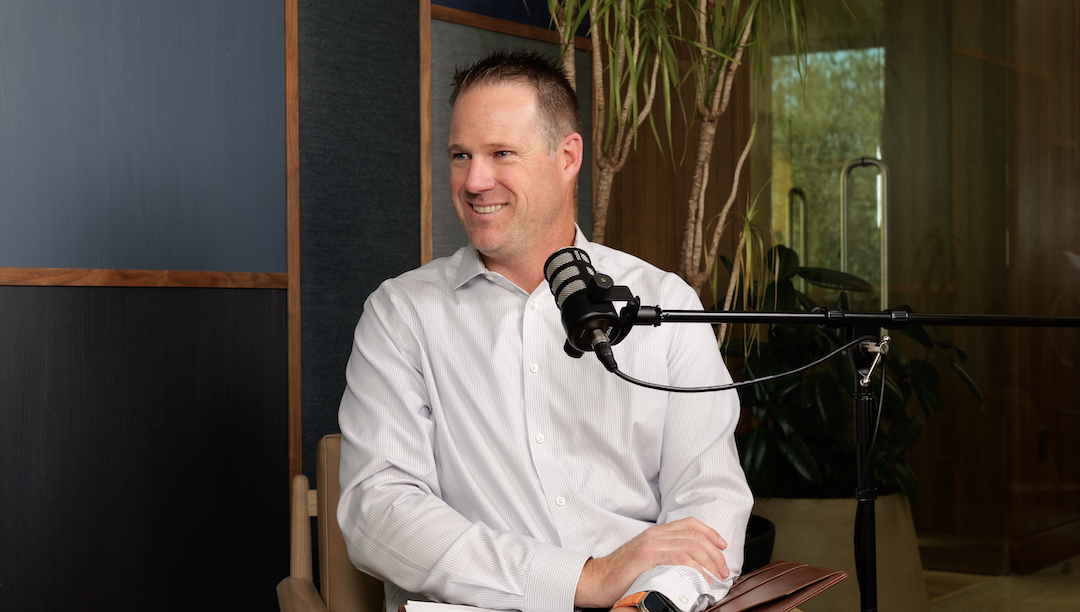
Kevin Rex, Wealth Advisor & Partner, Morton Wealth
Jeff Sarti, Chief Executive Officer & Partner, Morton Wealth
For most of the past four decades, buying real estate in California was as close to a guaranteed win as investing gets.
Prices rose. Interest rates fell. Demographics supported demand. People refinanced, pulled cash out, bought more, and built substantial wealth. That environment no longer exists.
In this episode of Financial Commute, CEO Jeff Sarti and Wealth Advisor Kevin Rex break down what drove real estate returns for 40 years, why those tailwinds have largely reversed, and what it takes to find genuine value in real estate today when the old playbook of closing your eyes and picking a property no longer works.
0:00 – Intro: mailbox money, mortgage rates, and the real estate reality check
0:51 – Welcome: Kevin and Jeff on when real estate stops being a good investment
1:48 – The past 40 years: why interest rates made real estate almost impossible to lose
3:56 – Demographics are shifting: baby boomers downsizing and younger generations opting out
6:17 – Buying in 2021 vs. 2026: how the math on a rental property completely changed
8:53 – Three ways to own real estate: individual property, REITs, or private partnerships
9:38 – Kevin's rental property war stories: why "mailbox money" is a myth
12:15 – Cap rates in California: when your yield is lower than your debt service
14:57 – REITs vs. private partnerships: why we prefer the private side
17:00 – Closing take: real estate is still a great asset class, you just have to be selective
Is real estate still a good investment?
Kevin and Jeff's answer is yes, but with an important qualification: it is no longer a close-your-eyes investment. For the past 30 years, buying almost any property in the right markets produced strong returns with minimal analytical effort. That was a function of two structural tailwinds, falling interest rates and growing demographics, that are no longer in place. Real estate can still generate strong returns. The difference is that finding those returns now requires expertise, selectivity, and a much more deliberate approach to geography, property type, and deal structure.
What is a cap rate and why does it matter?
A cap rate is the unleveraged yield on a real estate investment. The simple math: take the net income a property generates after expenses, divide it by the purchase price, and the result is the cap rate. A $1 million property generating $50,000 in net income has a 5 percent cap rate. The reason cap rates matter is that they tell you what the investment yields before you layer in debt. When borrowing costs are above 7 percent and the property yields 5 percent, the debt is more expensive than the asset is earning, which makes cash flow negative and makes the investment dependent entirely on price appreciation. That is a fundamentally different risk profile than owning a property where the income covers the debt service with room to spare.
Why did real estate appreciate so much from 1980 to 2020?
Two structural tailwinds ran in the same direction for 40 years. First, interest rates declined from roughly 18.5 percent on a 30-year mortgage in 1980 to near zero by 2021. Every year, debt got cheaper, which made real estate more affordable, pushed more buyers into the market, and supported higher prices. Second, the US population grew from 220 million to 360 million over that period, with the baby boomer generation, 80 million people born between 1946 and 1964, driving decades of household formation and home purchases. Both of those forces have now stalled. Population growth has flatlined. Interest rates have risen sharply from their lows. The tailwind that made close-your-eyes real estate investing work for a generation is no longer blowing.
Is it worth buying rental property in California right now?
The math is challenging. Cap rates in California are currently around 5 to 5.5 percent on small apartment buildings and investment properties. With 30-year mortgage rates above 7 percent, the cost of debt exceeds the yield on the asset, which means negative cash flow from day one. California also has poor demographic trends for an investment property: population growth has flatlined and turned negative in some recent years. None of this means California real estate can never appreciate. But it does mean that the investment case has to rest on something specific, a value-add strategy, a unique location, a below-market purchase, rather than on the assumption that prices will simply continue to rise.
What is the difference between a public REIT and a private real estate fund?
A public REIT is a stock that trades on an exchange. You can buy or sell shares daily, the companies are large and highly regulated, and the properties they own tend to be in the $50 million and above range because they have enormous amounts of capital to deploy. The downside is that REITs are crowded, meaning Wall Street institutions are all competing for the same assets, which tends to drive up valuations and drive down cap rates. A private limited partnership invests in smaller properties that institutions cannot efficiently target, has professional management on the ground, is not forced to deploy capital if opportunities are scarce, and typically involves partners who have their own money in the fund alongside investor capital. The trade-off is liquidity: you cannot sell a private fund position as easily as a public stock.
What are the real downsides of owning a rental property?
Kevin's answer is unusually candid because he owns one. The financial returns on his San Diego property, which he bought in 2012, have been strong. The experience has been anything but passive. He has driven to San Diego to appear in court for eviction proceedings. He has dealt with property damage, maintenance calls, and tenant disputes, including the story of a dog-related conflict that led to a three-month rent strike and cameras installed around the property. He has a property manager, and it still lands on his plate. His conclusion is not that individual rental properties are a bad investment, but that most people significantly underestimate how much time, attention, and stress comes with the mailbox money they imagine they will receive.
The instinct to invest in real estate is understandable and historically well-founded. Most people in California built meaningful wealth through property over the last four decades. But the conditions that made that wealth so accessible have materially changed, and understanding what drove those returns, and what has changed, is the starting point for making sound decisions about real estate in the current environment.
At Morton Wealth, real estate is one of our favorite asset classes and has been for decades. What has changed is not the asset class. It is the environment. If you want to talk through how real estate fits into your current portfolio and where the opportunities are today, that is exactly the conversation we are built for.
Stay & Renovate or Sell & Move? How to Decide
How to Evaluate Real Estate Funds
Disclosures: Educational content only, not investment advice or an offer of securities. Views are those of the speakers as of October 7th, 2026, and may change. Real estate and private fund investments involve risk, including loss of principal. Private funds are illiquid and available only to eligible investors. Past performance is not a guarantee of future results. Advisory services offered through Morton Wealth, an SEC-registered investment adviser. Registration does not imply a certain level of skill or training.